Assessment
Creditspring sells a membership: the borrower pays a fixed fee each month and can draw two interest-free loans a year, from ~$270 to ~$1,600 each, repaid over six months. Use it when the borrower expects to need a small sum and wants to know the full cost in advance. Do not join for a single loan, because the fee runs for the whole year.
Inclusive Finance Limited, which trades as Creditspring, is authorised by the Financial Conduct Authority (firm reference 786052). Its 2025 accounts show interest and fee income of ~$62M and an operating profit of ~$3M.
It fits a UK employee with a thin or damaged credit file who wants an alternative to an overdraft or a payday loan. It is a weaker fit for anyone who needs a large loan, or who would borrow only once a year.
Rating by criterion
Each of the eight criteria below is scored out of 100.
Sector criteria
Creditspring runs a soft credit check before it makes an offer, so checking eligibility leaves no mark on the credit file. Tiers run from Step at ~$270 a loan to Extra at ~$1,600, and the company says 68% of members move to a higher tier when they renew.
Money is drawn on demand from the member's account, twice a year. Ask how quickly a drawn loan reaches the bank account before relying on it for an urgent bill.
Repayments are fixed at six monthly instalments, with the first due around six weeks after drawing. The 2025 accounts show credit-loss impairments of ~$17M against ~$59M of interest income, so pricing assumes higher default rates than mainstream credit.
Creditspring sells direct to consumers and offers no partner API. On-time repayments can help the borrower's credit score, and late ones can hurt it.
Vendor criteria
Beyond loans, members get a free benefits finder and credit-building tools, including the Step tier for thin files. The core product is still two small loans a year.
Sign-up and the eligibility check run online, and the soft check shows a personal offer before the borrower commits.
Every tier shows the full cost up front. Creditspring charges no interest, and the membership fee is the cost of the credit. Core costs ~$16 a month for two loans of ~$485, which Creditspring states as a representative APR of 83.1%. Extra costs ~$35 a month for two loans of ~$1,600, a representative APR of 48.1%.
The membership runs for a year with the fee paid monthly, and a loan can be repaid early. Read the membership terms on cancelling before signing.
Against its peers
Small-loan and pay-advance lenders that buyers often compare to Creditspring.

Fact file
| Legal entity | Inclusive Finance Limited, company 10522518 |
|---|---|
| Regulator | Financial Conduct Authority, firm reference 786052 |
| 2025 interest and fee income | ~$62M |
| 2025 operating profit | ~$3M |
| Loan sizes | ~$270 to ~$1,600, twice a year |
Comparisons
- Creditspring vs Beforepay
- Creditspring vs Fair Finance
- Creditspring vs Lending Stream
- Abound vs Creditspring
Key leadership
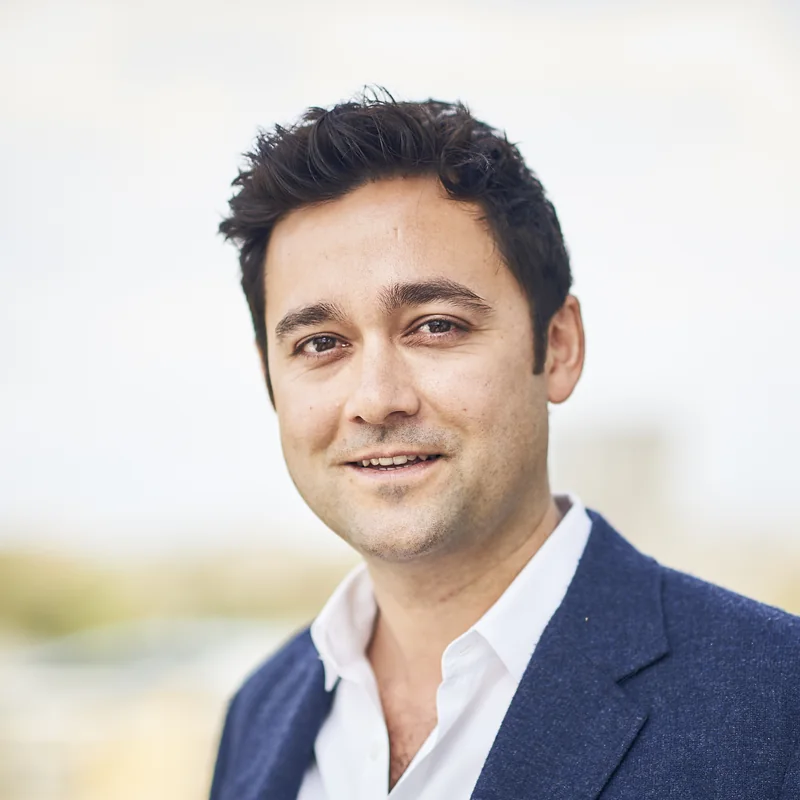
Neil Kadagathur co-founded Creditspring in 2016 and is chief executive. Hannah Matson is chief operating officer.
How this review was created
This profile gives our own assessment of Creditspring to companies selecting a Lending & credit infrastructure provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Creditspring gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, and filings. Fact-checking took place on October 21, 2026.