Assessment
Beforepay is a short pay advance and small personal loan for employed Australians who need cash before payday or for a larger expense. Pay Advance puts A$50 to A$2,000 into a linked bank account, repaid within 62 days in line with the user’s pay cycle; Personal Loans cover A$2,001 to A$5,000 over 3 to 12 months.
For the year ended 30 June 2026, Beforepay Group reported revenue of A$50.6 million (about US$33 million at roughly 0.66 AUD/USD), up 26% from A$40.3 million. Statutory net profit after tax (NPAT) was A$8.2 million, and cash NPAT was A$15.7 million. Total advances reached A$963 million. Growth came from larger average Pay Advances, new pricing on Pay Advances, and fast growth in Personal Loans.
Beforepay fits employed Australian residents with a regular wage who want a regulated app-based advance or small personal loan. It is a weaker fit for people without regular employment income, for businesses, or for anyone who needs a large mortgage-style loan.
Rating by criterion
Each of the eight criteria below is scored out of 100.
Sector criteria
For loans of A$5,000 or less, Beforepay’s calculator FAQ says both Pay Advance and Personal Loans are assessed by connecting to the user’s bank account and reviewing income and spending, without a traditional credit-bureau check. Eligibility includes age 18+, Australian residency, regular wages, less than 51% of income from Centrelink (the government agency that pays welfare benefits), and acceptable ID. Users can only have one active Beforepay loan at a time, which stops them piling up several loans.
The company markets approval in under 60 seconds for many applications and money in as little as five minutes once approved. People apply directly through the website and app, with no broker or employer payroll connection needed. Speed is the main promise, though some applications still go to slower manual review.
FY26 net bad debts (write-offs divided by total advances) rose to 0.5% from 0.2%, which management tied partly to higher losses on Personal Loans and to an unusually low Pay Advance figure the year before. Pay Advance repayments are timed to the user’s pay cycle. The product pages list no late fees and no early-repayment fees, though interest still accrues on any outstanding balance.
Beforepay is built around connecting to the user’s bank account, budgeting tools, and loan status in the app. Its integrations serve consumers and do not connect to employers’ payroll systems. The current offer is sold directly to consumers, which makes it a different product from earned-wage access offered through an employer.
Vendor criteria
In FY26 Beforepay grew Personal Loans sharply (company materials cite Personal Loan revenue up several times over), started charging interest on Pay Advances, and took on a new, cheaper debt facility. Free budgeting and spending tools come with the credit products. For FY27 the company points to the full-year effect of the new pricing and a larger loan book.
Users sign up online or in the app: they create an account, connect a bank, and choose a loan. The group site lists a support email (support@beforepay.com.au). The calculator gives an estimate, and the credit contract sets the actual terms.
Beforepay publishes a clear cost model on its Pay Advance calculator page: a fixed 5% setup fee plus interest up to 24% p.a. on the reducing balance, with a Personal Loan comparison-rate example of 29.50% p.a. on a A$2,500 loan over two years. That is clearer than most payday-style lenders, though the contract rate can differ from the calculator’s maximum.
A Pay Advance runs for at most 62 days, in up to four instalments. Personal Loans run 3-12 months. Beforepay advertises no late fees and no early-repayment fees. The credit contract governs the exact schedule. Users cannot hold two active Beforepay loans at once.
Against its peers
Pay advance and small-loan providers that buyers often compare to Beforepay.


Fact file
| Exchange | ASX: B4P |
|---|---|
| FY26 revenue | A$50.608 million (~US$33M) |
| FY26 statutory NPAT | A$8.2 million |
| FY26 cash NPAT | A$15.7 million |
| FY26 total advances | A$963 million |
| Pay Advance | A$50-A$2,000; up to 62 days |
| Personal Loan | A$2,001-A$5,000; 3-12 months |
| Claimed reach | Company marketing cites over 2 million Australians |
Comparisons
- Beforepay vs EarnIn
- Beforepay vs Dave
- Beforepay vs a traditional Australian personal lender
- Creditspring vs Beforepay
Key leadership
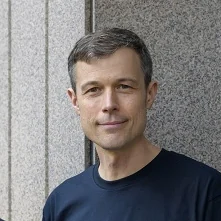
Jamie Twiss is chief executive, Kasey Kaplan is deputy chief executive, Laavanya Pari is chief financial officer, and Rajini Carpenter is chief technology officer.
How this review was created
This profile gives our own assessment of Beforepay to companies selecting a Lending & credit infrastructure provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Beforepay gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, and filings. Fact-checking took place on October 5, 2026. The summary line for this company, which also appears on the Companies and sector pages, shows loan limits in US dollars, converted from Australian dollars at the Federal Reserve H.10 rate of $0.7037 per Australian dollar on October 23, 2026.