Assessment
Abound reads a borrower's bank transactions through open banking and uses them, with the credit file, to decide whether to lend and at what rate. Use it when a borrower has a thin or patchy credit history but steady income. Loans run for at least 12 months, so it is not a source of short-term cash.
Abound was founded in London, England, in February 2020 by Gerald Chappell and Michelle He and began lending in 2021. It reports 2024 revenue of ~$88M with ~$12M of profit before tax, more than ~$2.0B of loans originated, and it topped the Sunday Times 100 Tech list in 2026.
It fits a UK employee with regular income in a bank account who wants a mid-size personal loan repaid over several years. Render fits a bank or lender that wants affordability checks built on transaction data. It is a weaker fit for anyone who will not link a bank account.
Rating by criterion
Each of the eight criteria below is scored out of 100.
Sector criteria
Abound underwrites on bank-transaction data as well as credit files, which lets it offer lower rates to borrowers with patchy scores. It says its default rates run 50% to 70% below market benchmarks.
Borrowers apply online and link a bank account. The minimum term is 12 months and the representative APR is 21.8%, so compare the full cost with a bank loan before accepting.
Abound reached a profit two and a half years after it began trading. Borrowers can take repayment holidays and adjust repayments to a real-time view of what they can afford.
Render lets other lenders run the same decisioning inside their own systems. Live partner launches include IVF finance with Gaia and a card with LemFi.
Vendor criteria
Abound has moved from personal loans into Prime loans with Citi, retail finance and mortgages, and entered Spain in 2025. Render is growing as a share of revenue.
Borrowers apply online; a lender buying Render goes through a sales and integration project. Ask how long a Render pilot takes before planning a launch.
The representative APR is published, and each borrower sees a personal rate before signing. Render pricing is not published.
Loan terms start at 12 months, and repayments can be changed. Read the early-repayment terms before borrowing.
Against its peers
Personal lenders and credit-decisioning vendors that buyers often compare to Abound.
Fact file
| Lending entity | Fintern Ltd, company 12472034, FCA authorised |
|---|---|
| 2024 revenue | ~$88M, with ~$12M profit before tax |
| Loans originated | More than ~$2.0B |
| Loan financing | ~$3.0B from Citi, Deutsche Bank, Waterfall and others |
| Representative APR | 21.8% |
Fair Finance is a London social enterprise lender that makes small personal loans to people with poor or thin credit files, so it reaches borrowers further down the credit range with smaller loans.
Comparisons
Key leadership
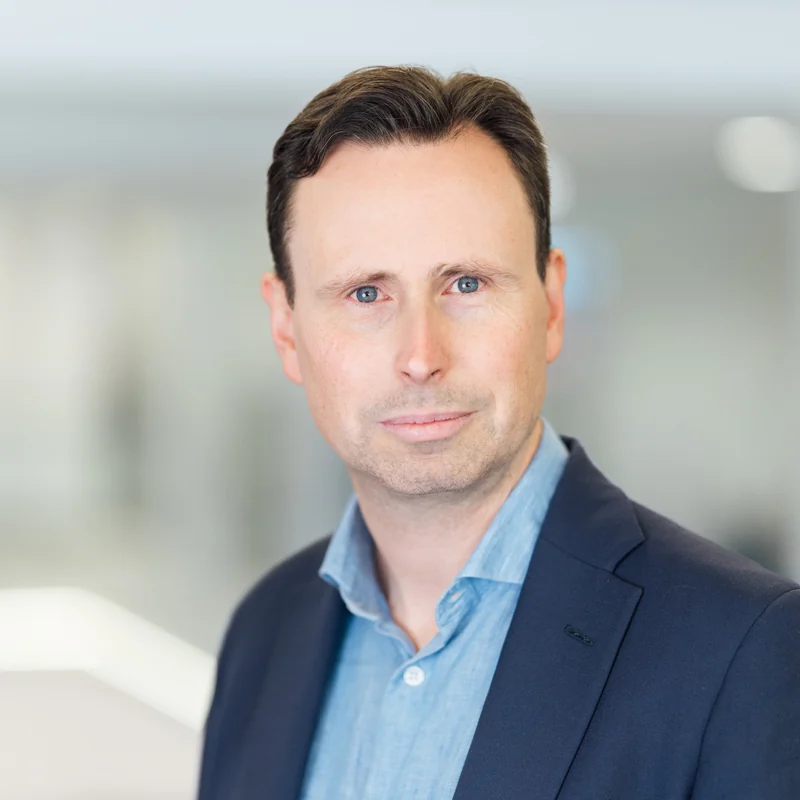
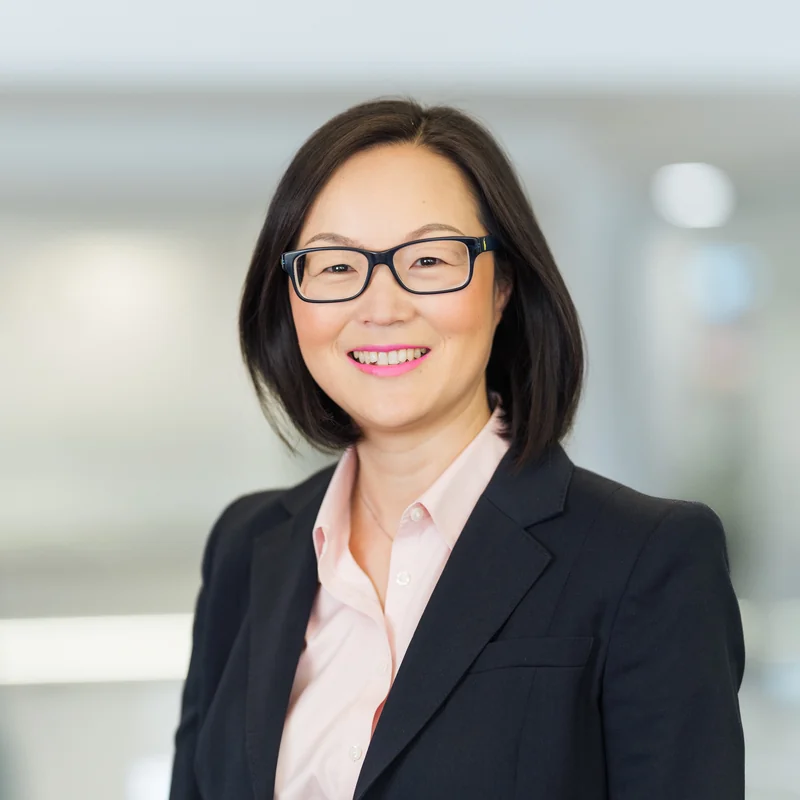
Gerald Chappell co-founded Abound in 2020 and is chief executive. Dr. Michelle He, the other co-founder, is chief operating officer.
How this review was created
This profile gives our own assessment of Abound to companies selecting a Lending & credit infrastructure provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Abound gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, and filings. Fact-checking took place on October 22, 2026.