Assessment
Yapily provides open-banking payments and account data over one UK/EU API for product teams that want Pay by Bank and bank-data analysis without stitching multiple providers. It sells payments APIs (single payments, bulk payments, variable recurring payments) and data APIs (account information, enrichment). Yapily Connect lets a customer go live under Yapily's regulated licences when the customer does not yet hold its own permission to read account data (an AISP licence) or start payments (a PISP licence), including connections to business bank accounts.
For the year ended 31 December 2025, Yapily's group accounts, filed at Companies House on 22 September 2026, and press coverage of the results put turnover at about £16.7 million, up from about £6.7 million in 2024, with a statutory profit of about £355,000 after a prior-year loss. Chief executive Stefano Vaccino has credited a lean cost base and more revenue from existing customers, which October 2026 coverage said include Revolut, Intuit, Adyen, and Google. Press reports put headcount at 102 at the end of 2025. Yapily's last funding round was a Series B in 2021, and in early October 2026 it said it preferred to grow organically while other open-banking companies merged.
Yapily fits a UK or European fintech, payment service provider (PSP), lender, or software vendor that needs payments initiation and account data through one provider, including teams that want to launch under Yapily Connect before holding their own open-banking licence. It is a weaker fit for a product built around US bank connections of the kind Plaid offers, or for a buyer that wants a published per-call rate card before talking to sales.
Rating by criterion
Each of the eight criteria below is scored out of 100.
Sector criteria
Yapily's payments products cover single Pay by Bank payments, bulk payments, sweeping variable recurring payments that move money between a person's own accounts, and commercial variable recurring payments for one-click and recurring checkout. Data products cover account information and enriched, categorised transaction data used for onboarding, affordability checks, and personalisation. Yapily connects to UK and European banks, and its marketing site cites about 2,000 banks and institutions in about 19 countries. Yapily does not offer card issuing.
Yapily markets its API to developers, with documentation, sandboxes (test environments), and tools meant to get an integration into production faster. It says more than 3,500 customer applications run on its API. In open banking, the share of users who finish a payment depends on uptime, on how bank-connection outages are handled, and on how the API reports failed consent and strong customer authentication (SCA) checks, as much as on the number of endpoints.
Yapily Connect Ltd, a UK subsidiary, is regulated by the Financial Conduct Authority (FCA number 827001), and Yapily Connect UAB is regulated by the Bank of Lithuania (licence LB002045) for EU services. Those licences let customers rely on Yapily as the regulated provider for account data, payments, or both, while users see the customer's own brand. A buyer with its own third-party provider (TPP) licence can still use Yapily's bank connections. Yapily Connect is for teams that do not want to become a regulated TPP before they launch.
Yapily markets itself to payment providers, banks and e-money institutions (EMIs), lenders, and accounting and ERP software companies. Customers listed on its site and in press include Pleo, Crezco, Yonder, and Volume, and Vaccino has cited larger customers such as Revolut, Intuit, Adyen, and Google. Business open-banking products depend on bank coverage across Europe that includes business accounts, which is where Yapily puts its emphasis.
Vendor criteria
In 2025 Yapily invested in engineering ahead of wider use of commercial variable recurring payments, stricter quality expectations under PSD3 (the EU's next payment services directive), and the EU's Financial Data Access (FiDA) open-finance rules, which Vaccino has flagged for 2027-2028. Payments and data run on one platform. For a buyer, the roadmap depends on how current Yapily's bank coverage is and how ready its variable recurring payments are in each country where the product will launch, and both can differ by country.
Yapily Connect is meant to shorten the time to launch for a customer without its own licence. Yapily's site promises expert support from integration onward, but it does not publish chat hours or a support SLA.
As of 5 October 2026, Yapily's pricing page describes flexible, usage-based terms and says there are no hidden fees, but it lists no per-call or per-payment prices for production use. Prices come from the sales team, typically as a monthly platform fee plus usage charges, with volume discounts.
Yapily does not publish contract length, minimums, or exit terms. Whether a customer uses its own TPP permissions or Yapily Connect changes who carries the regulatory responsibility, so the order form has to say which applies. A fair comparison of contract terms with TrueLayer or Token.io needs each vendor's clauses on data retention, liability for bank outages, and help at termination.
Against its peers
Open-banking connectivity vendors that buyers often compare to Yapily.

Fact file
| Products | Open-banking payments APIs; account-data APIs; Yapily Connect (licensed access) |
|---|---|
| Turnover YE 2025 | About £16.7 million (press quoting company / group accounts; up from about £6.7 million in 2024) |
| Profit YE 2025 | About £355,000 statutory profit (press); company also cited positive EBITDA / operating profit figures in founder commentary |
| Staff YE 2025 | 102 (press quoting company) |
| Coverage (company-stated) | ~2,000 banks/institutions; ~19 countries; 3,500+ customer applications |
| Regulation | Yapily Connect Ltd FCA 827001 (UK); Yapily Connect UAB Bank of Lithuania LB002045 (EU) |
| Funding | Series B US$51 million in 2021 (Sapphire-led); nearly US$70 million raised total per company about page |
| Customers cited in press/site | Revolut, Intuit, Adyen, Google (CEO/press); Pleo, Crezco, Yonder, Volume (site case references) |
Comparisons
Key leadership
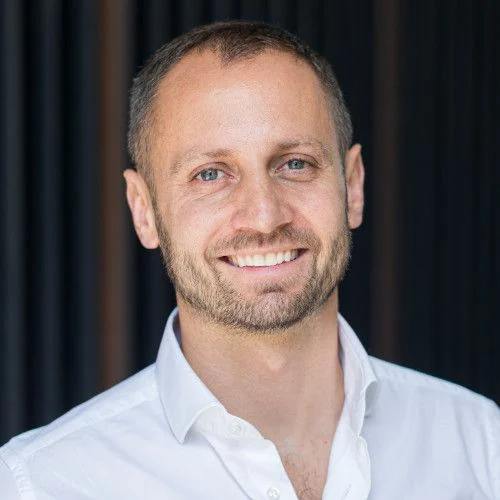
Stefano Vaccino founded Yapily and is chief executive. Gerd Hoxha is chief operating officer.
How this review was created
This profile gives our own assessment of Yapily to companies selecting a Payments & acquiring provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Yapily gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, and filings. Fact-checking took place on October 5, 2026.