Assessment
Ocrolus is used by small business lenders, consumer lenders, and mortgage lenders that underwrite from documents. The company says it analyzes about 750,000 credit applications a month, and its best use cases are bank-statement analysis, income verification, cash-flow analytics, and document fraud detection. Pricing is quote-based, and its main competitors are Inscribe, Plaid, and in-house document teams.
Sam Bobley and a high school friend started Ocrolus in 2014, first to help elder law attorneys review bank statements for Medicaid applications. An $80M Series C led by FinVC in September 2021 valued the company at more than $500M, and total funding is about $110M. Customers have included Brex, Enova, LendingClub, PayPal, and SoFi.
It fits a lender that receives large volumes of PDFs and scans and wants clean data with human review behind the AI. It is a weaker fit for a lender that already relies on direct account data feeds and only needs light document checks.
Rating by criterion
We score each of the eight criteria out of 100.
Sector criteria
Feed bank statements, pay stubs, and tax forms into cash-flow and income analytics for underwriting.
Speed up funding decisions with fast document turnaround. Human review handles low-confidence fields.
Flag tampered documents with built-in fraud detection before credit decisions.
Connect through the API or lending platform partners. Output feeds loan origination systems.
Vendor criteria
Expect expansion across small business, consumer, and mortgage lending.
Plan an API integration and a calibration period on your document mix.
Ask for a quote. Per-document or per-application pricing is not posted.
Negotiate by volume. High-volume lenders have more room on unit price.
Against its peers
Underwriting data and decisioning vendors that buyers often compare to Ocrolus.

User comments
- Upside
- Upside
- Downside
Fact file
| Co-founder and CEO | Sam Bobley |
|---|---|
| Founded | 2014, New York |
| Volume | ~750,000 credit applications a month (company figure) |
| Series C | $80M, September 2021, led by FinVC |
| Example customers | Brex, Enova, LendingClub, PayPal, SoFi |
Comparisons
Key leadership
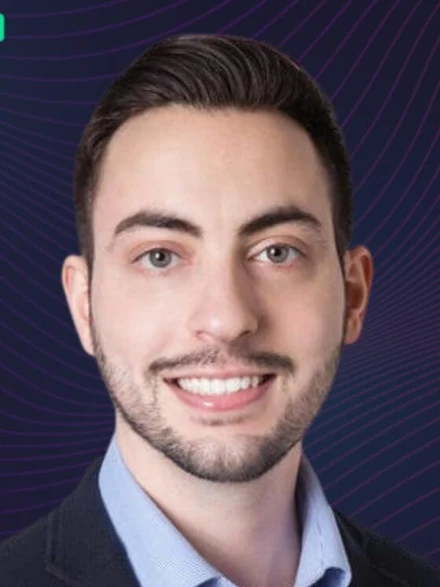
Sam Bobley co-founded Ocrolus in 2014 and is its chief executive.
How this review was created
This profile gives our own assessment of Ocrolus to companies selecting a Lending & credit infrastructure provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Ocrolus gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, public reviews and filings. Fact-checking took place on November 9, 2026.
Source pages
- Ocrolus home page: https://www.ocrolus.com/ (As of November 9, 2026)
- Ocrolus company page: https://www.ocrolus.com/company/ (As of November 9, 2026)
- TechCrunch, September 2021: https://techcrunch.com/2021/09/23/ocrolus-lands-80m-to-automate-document-processing-for-fintechs-and-banks/ (As of November 9, 2026)
- Fintech One-on-One, Sam Bobley: https://fintechoneonone.com/sam-bobley-co-founder-ceo-of-ocrolus/ (As of November 9, 2026)